The month has come to an end. Sales were excellent, and the P&L shows a profit and there is nothing to be seriously off.
Check the restaurant’s bank account.
You didn’t get the call you had hoped for.
For owners of restaurants, this disconnection can be a source of frustration because profits and cash flow seem like they should be the same. They don’t. A P&L evaluates the financial performance of a firm for a particular time period, whereas an account in a bank shows the exact timing of money entering and leaving the company.
Knowing the difference can change how a restaurant’s owner views their finances.
Imagine what could happen on an average week. Food is paid for by customers. Employees have to be paid. Deliveries of food and beverages arrive with invoices. Rent is getting closer. Credit card deposits are subject to their own timetable. Sales tax is collected, but it is a responsibility.
Already the shopping spree for next week have started.
Focusing on revenue only or the final profit figure isn’t a good way to assess the full scope of what happens.
The Secret Could Be Hidden in the Prime Cost
If the profitability of restaurants begins to decline, the costs of food, beverages and labor expenses should be taken into the equation.
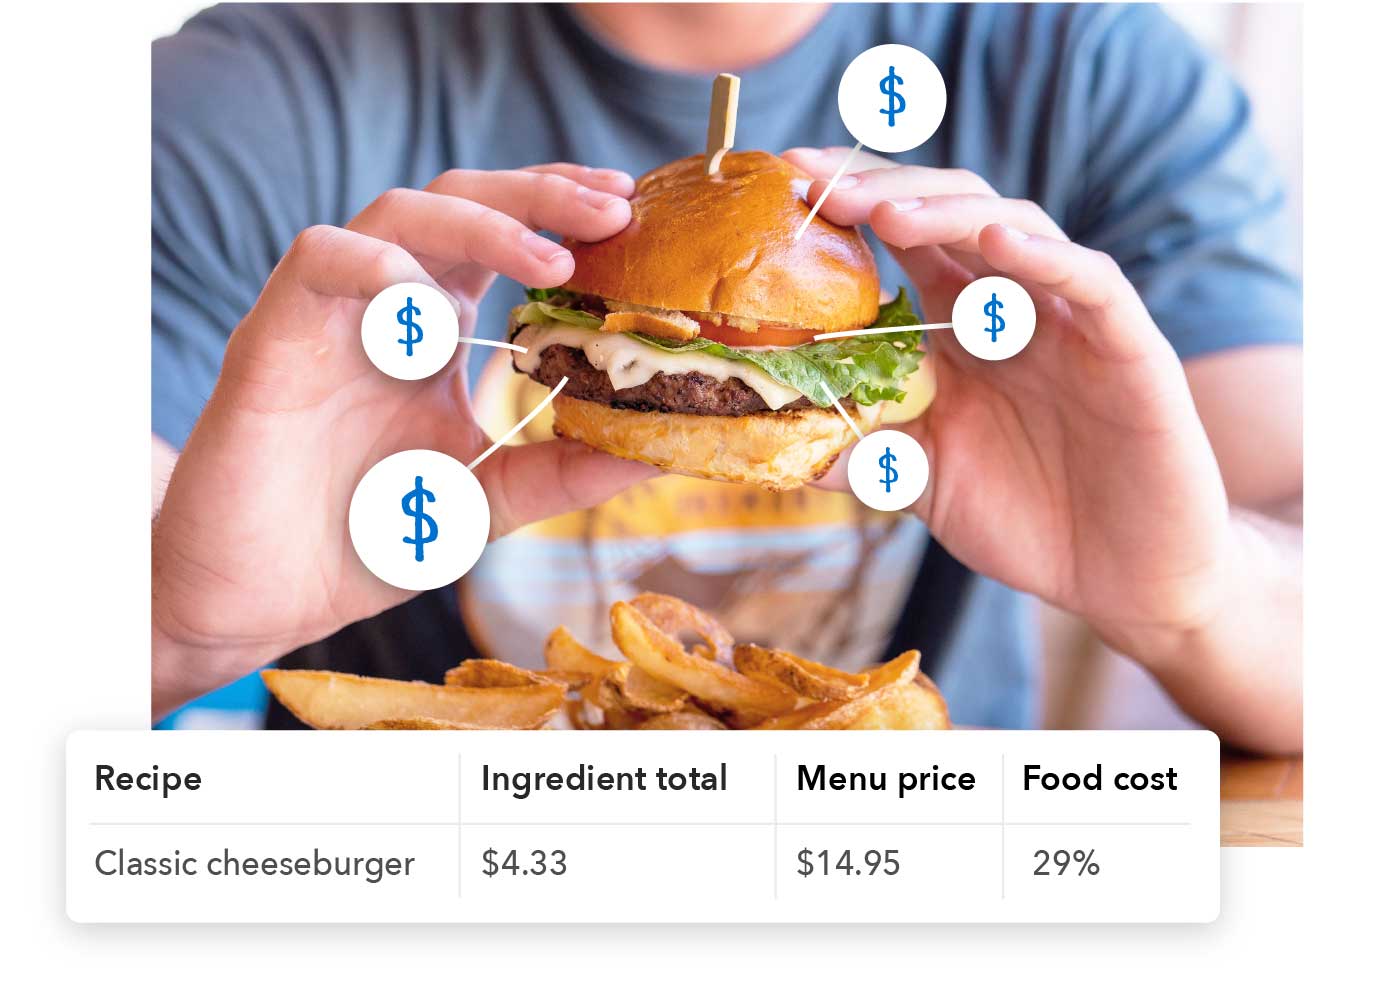
Cost of sales combined with labor is a major cost. The Bookkeeping Chef’s guidance puts the cost of goods sold at 60% to 65 percent for a wide range of restaurants and focuses on weekly monitoring rather than waiting until the end the month.
Effective prime cost management is less about obsessing over a single percentage and more about noticing movement early.
Let’s say that typically, the restaurant does well, but this week, it’s more of a percent. Perhaps the overtime rate was increased. The cost of beverages could remain the same, while food costs increased. A higher food percentage might make the supervisor think about reviewing buying, waste, menu mix, portions or invoices from vendors.
The percentage raises questions. The answer is found in the activity of the restaurant.
A weekly report makes an opportunity for conversation while everyone will be able to recall what occurred.
The details will be more difficult for you to recall after a couple of days.
Once the vendor invoices are received
Restaurants might purchase food items one week and pay for them the next. This explains why profits alone won’t be able to answer every cash-related question.
Invoices from vendors have to be accounted for, tracked and paid. This is a lot of work in an operation that has several suppliers.
Automating the accounts payable process can streamline this process by reducing the repetitive handling of bills and payments. Bookkeeping systems that are connected to accounting systems can provide owners with a clear understanding of their obligations, even though they haven’t yet been paid.
This is useful, because the bank’s balance could appear healthier than a restaurant’s real near-term situation.
There is currently $80,000 on the account. The $80,000 figure means very little if vendors, rent or payroll take up a large portion over the next few days.
Cash flow forecasting is a natural result.
What happens to our cash once we’ve received the cash we’ve been expecting and have fulfilled all of our obligations?
It is crucial to understand the difference when deciding if this week is the best time to replace equipment, purchase additional items, or conserve liquid funds.
You may not have been rightfully entitled to all the money you thought.
The sales tax illustrates this in particular.
Restaurants collect cash from its customers, which eventually has to be managed according to tax requirements. If those funds are divided into operating money, the bank’s balance can give a false idea of what’s there to be spent.
Regularly updated records ensure sales tax compliance, while giving management a more realistic understanding of the restaurant’s financials.
This is one reason why restaurant accounting is more efficient when financial responsibilities aren’t treated as distinct islands.
Prime cost affects margin. COGS (cost of goods sold) and future payments are affected due to purchases made by vendors. Payroll affects the amount of cash available and also the labor percentage. Sales tax impacts the availability of cash. The P&L documents financial performance while forecasting helps management look ahead.
The pieces link.
Bookkeeping Chef is a restaurant-specific report that integrates through system integrations. If you don’t want to spend their nights manually reconciling financial data, outsourced bookkeeping services can handle the bulk of accounting tasks without removing the owner of the financial discussions.
It’s the last part that’s important.
Restaurant owners shouldn’t be able to stop studying the literature even if they’re managed by another. Owners need to be informed which will allow them to comprehend what’s happening.
Don’t think that the P&L is incorrect if the accounts appear to be in a good state, yet the P&L shows the restaurant has made money.
Find out what transpired between you and your spouse.
The answer to this question will provide more information about the restaurant’s reputation than the number.